A comprehensive retirement plan coordinates the financial decisions that affect your lifestyle today and your income later. It brings retirement income, Social Security, investments, taxes, estate...
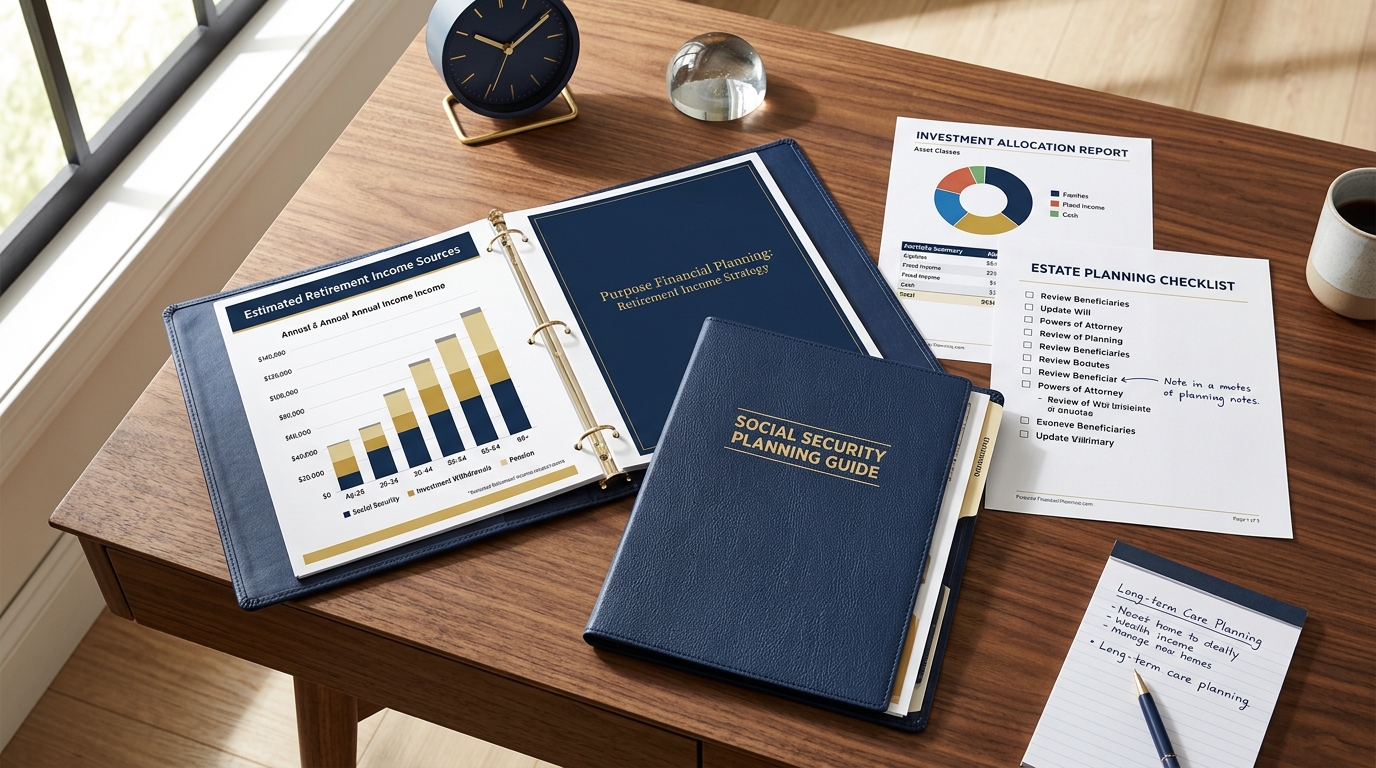
A comprehensive retirement plan coordinates the financial decisions that affect your lifestyle today and your income later. It brings retirement income, Social Security, investments, taxes, estate planning, long-term care considerations, and day-to-day cash flow into one organized strategy. Rather than treating each decision separately, Purpose Financial Planning helps clients see how one choice can influence the others.
For retirees and pre-retirees in Schaumburg and the surrounding northwest suburbs, the goal is not to predict every future event. It is to make informed decisions, understand tradeoffs, and create a plan that can be reviewed as life, markets, tax rules, and personal priorities change.
Why a Comprehensive Plan Matters
Financial decisions rarely operate in isolation. A decision about when to claim Social Security can change the amount you need to withdraw from investment accounts. A large retirement-account distribution may affect taxes and Medicare-related costs. An outdated beneficiary designation can undermine the intentions stated in a will or trust.
A comprehensive financial plan provides a framework for connecting these decisions. Purpose Financial Planning takes an education-first approach, helping clients understand the assumptions, choices, and risks behind their plan before important decisions are made.
Creating a Retirement Paycheck Strategy
Many people spend decades accumulating savings but have not yet determined how those savings will become retirement income. A retirement paycheck strategy addresses that transition. It considers essential expenses, discretionary spending, predictable income sources, account balances, inflation, market conditions, and the length of retirement.
Retirement withdrawal planning is not simply a matter of selecting a fixed percentage from a portfolio. Withdrawals may need to come from different account types at different times, and spending may change with travel, housing decisions, health needs, or family priorities. A coordinated retirement income plan can help clarify which resources may be used first and how the approach may be adjusted over time.
For example, a household may combine Social Security benefits, pension income, taxable savings, traditional retirement accounts, and Roth accounts to support cash flow. The order and timing of those sources can have tax and longevity implications. Purpose Financial Planning helps clients in Schaumburg evaluate these choices within their broader retirement income strategy.
Coordinating Social Security With Other Income Sources
Social Security claiming is an important decision because monthly benefits can vary based on when benefits begin. The right timing depends on individual circumstances, including health, employment plans, marital status, survivor-income needs, taxes, and the household’s other available resources.
Waiting until age 70 may increase an individual’s monthly retirement benefit, but waiting is not automatically the best choice for everyone. Likewise, claiming early can provide income sooner but may permanently reduce the monthly benefit. Married couples also need to consider spousal benefits and survivor benefits, particularly when one spouse has a materially higher earnings record.
Social Security planning should be coordinated with retirement withdrawals and cash flow. A thoughtful claiming strategy can show how different benefit dates may affect portfolio withdrawals, taxes, and income available to a surviving spouse. Daniel Kaibel, CFP, RSSA, works with clients to evaluate Social Security options in the context of their full financial picture.
Managing Investments for Retirement Income
Investment management remains important in retirement, but the focus often changes. Instead of concentrating only on growth, a portfolio may need to support withdrawals while remaining aligned with a household’s time horizon, risk tolerance, liquidity needs, and legacy goals.
Asset allocation can help balance the need for growth with the need for stability. It also helps address sequence-of-returns risk: the possibility that poor market performance early in retirement, combined with withdrawals, could have an outsized effect on long-term portfolio sustainability. This risk cannot be eliminated, but it can be considered when building a retirement distribution strategy.
Regular portfolio reviews can keep investments connected to the retirement plan rather than allowing them to operate independently. At Purpose Financial Planning, investment management is considered alongside income needs, tax considerations, and planned withdrawals—not as a separate exercise.
Making Taxes Part of the Planning Conversation
Taxes can affect how much retirement income is available to spend. Traditional IRA and 401(k) withdrawals are generally taxable, while Roth account withdrawals may receive different tax treatment when applicable requirements are met. Taxable investment accounts, capital gains, required minimum distributions, and Social Security taxation can also influence the household tax picture.
Tax-aware planning considers the timing and source of withdrawals. It may include evaluating distributions before required minimum distributions begin, coordinating charitable giving where appropriate, or considering whether a planned withdrawal could move a household into a higher tax bracket. These decisions should be made in coordination with a qualified tax professional.
The purpose is not to promise lower taxes. It is to make tax considerations visible before financial decisions are finalized, so the retirement plan reflects after-tax cash flow as well as account balances.
Coordinating Estate Planning and Beneficiary Decisions
Estate planning coordination helps ensure that financial accounts, legal documents, and personal intentions are working in the same direction. A will or trust may be central to an estate plan, but retirement accounts and life insurance policies often pass through beneficiary designations. Those designations should be reviewed alongside the broader plan.
A comprehensive review may also identify the need to discuss powers of attorney, healthcare directives, guardianship concerns, and successor decision-makers with an estate planning attorney. Financial professionals do not draft legal documents unless separately qualified to do so, but they can help identify planning gaps and coordinate information with the client’s legal team.
Purpose Financial Planning helps clients organize questions for an estate planning checkup and understand how retirement accounts, beneficiaries, and legacy objectives may connect.
Planning for Long-Term Care and Extended Care Costs
Medicare generally does not cover most long-term custodial care. As a result, extended care can create a significant planning question for retirees and their families. A long-term care plan may involve personal savings, insurance, hybrid long-term care coverage, family support, or a combination of resources.
The appropriate approach depends on health history, assets, income, family circumstances, and personal preferences. Planning ahead can help households consider how care costs could affect retirement income, investment withdrawals, and a surviving spouse’s financial security. It can also clarify which questions should be discussed with insurance and legal professionals.
Using Cash Flow to Keep the Plan Grounded
Cash flow planning turns broad financial goals into practical decisions. It begins with an honest picture of spending: essential costs, lifestyle expenses, debt payments, housing, insurance, travel, gifts, and potential healthcare needs. In retirement, cash flow also helps identify how much portfolio income may be required in a given year.
A detailed cash flow view is useful before retirement and after retirement. For pre-retirees, it can help answer whether a target retirement date is realistic. For retirees, it can show whether income sources and withdrawals are aligned with actual spending. It also gives the plan a foundation for evaluating changes, such as a home repair, family assistance, market volatility, or a change in health.
One Plan, Reviewed as Life Changes
A comprehensive financial plan is not a one-time document. It is an ongoing process of reviewing assumptions and coordinating decisions. A job change, business transition, market movement, inheritance, loss of a spouse, health event, or tax-law update can all create a reason to revisit the plan.
Purpose Financial Planning serves individuals, families, retirees, pre-retirees, and business owners throughout Schaumburg, Arlington Heights, Hoffman Estates, Barrington, Lake Zurich, and Itasca. Our independent planning process brings retirement income, Social Security, investments, estate planning coordination, long-term care planning, cash flow, and taxes into a clearer conversation.
FAQ
What does comprehensive financial planning include?
Comprehensive financial planning can include retirement income planning, investment management, Social Security analysis, cash flow planning, tax-aware withdrawal coordination, estate planning coordination, long-term care considerations, insurance reviews, and business-owner planning. The exact scope should reflect the client’s needs and goals.
How do Social Security and retirement withdrawals work together?
Social Security benefits can reduce the amount that must be withdrawn from savings, while the timing of benefits may require greater or lesser portfolio withdrawals in the short term. Reviewing both together can help show the potential effects on taxes, cash flow, investment risk, and survivor income.
Do I need estate planning if I already have a will?
A will is an important legal document, but it may not control assets that transfer by beneficiary designation or joint ownership. A coordinated review can help identify whether beneficiary forms, account titles, powers of attorney, and other documents should be discussed with an estate planning attorney.
Does Medicare cover long-term care?
Medicare generally does not cover most long-term custodial care, such as ongoing help with daily activities. Limited skilled-care coverage may be available in specific circumstances. A long-term care plan can help evaluate potential funding options and their effect on retirement resources.
When should I start retirement planning?
It is useful to begin well before retirement, but planning can add value at many stages. Pre-retirees may need to evaluate savings, retirement timing, Social Security, and income needs. Retirees may benefit from reviewing withdrawals, taxes, investments, estate coordination, and care planning as circumstances change.
If you are seeking straightforward, personalized financial guidance in Schaumburg or the surrounding northwest suburbs, contact Purpose Financial Planning to schedule a consultation. We can discuss your priorities and help you determine whether a coordinated financial planning process is appropriate for your situation.
Our Services
About the Author
Daniel Kaibel is the founder of Purpose Financial Planning, an independent financial planning firm serving Schaumburg, Illinois and the surrounding northwest suburbs. With more than 30 years of financial services experience, Dan has built the firm around straightforward advice, personalized guidance, and helping clients make informed decisions with greater confidence.
At Purpose Financial Planning, Dan works with retirees, business owners, families, and individuals to coordinate retirement planning, investment management, Social Security strategies, and long-term financial goals. His approach is simple: understand what matters most to the client, explain options in plain language, and create a clear path forward so financial decisions feel less overwhelming and more manageable.