Year-end is an important opportunity for business owners to evaluate how the company’s financial performance supports personal retirement, future growth, and an eventual transition. A focused...
Year-end is an important opportunity for business owners to evaluate how the company’s financial performance supports personal retirement, future growth, and an eventual transition. A focused review of cash flow, retirement plan funding, taxes, business continuity, and business value can help turn separate decisions into a more coordinated plan. For Schaumburg-area owners, the objective is not simply to close the books—it is to clarify what the business needs to provide now and what it may need to deliver later.
Start With a Clear Cash Flow Review
Cash flow is the practical foundation of business owner planning. Before making year-end commitments, review how money moved through the business: operating revenue, recurring expenses, owner compensation, debt obligations, capital purchases, and irregular costs. Compare actual results with the expectations you set earlier in the year, then identify the factors that created meaningful differences.
A useful review also separates business cash from personal spending needs. Many owners draw funds from the company as needs arise, which can make it difficult to see whether the business is consistently supporting their lifestyle, savings goals, and future retirement income needs. Establishing a clearer picture of available cash can improve decisions about reserves, reinvestment, compensation, and retirement plan contributions.
At Purpose Financial Planning LLC, our comprehensive financial planning process helps owners connect business cash flow planning to their broader household goals. This can be especially valuable when the business is a primary source of both current income and long-term wealth.
Review Retirement Plan Contributions Before Year-End
Business retirement planning deserves more than a last-minute decision. Review the retirement plan available through your company, the contributions already made, and the potential funding that may remain appropriate based on your business results and personal objectives. Depending on the plan design, business owners and employees may have different contribution opportunities and deadlines.
Rather than viewing contributions only as an annual expense or a tax-related decision, consider their role in building assets outside the business. A retirement account can become an important source of flexibility when markets, business conditions, or your eventual exit timeline do not unfold exactly as expected.
Contribution rules, eligibility requirements, deadlines, and tax treatment can be complex. Your tax professional and plan administrator should provide guidance on the choices available to your business. Purpose Financial Planning can help you evaluate how retirement savings fit into an overall retirement income strategy and investment plan.
Coordinate Estimated Taxes With Your Tax Professional
Year-end financial planning should include a timely conversation with your CPA or tax professional. Review year-to-date income, estimated tax payments, projected taxable income, owner compensation, distributions, and expected changes before the calendar year closes. This discussion can help identify whether projections and cash reserves still align with your expectations.
Purpose Financial Planning does not provide tax or legal advice. However, financial planning can help organize the information and decision points that may be useful for conversations with your qualified tax and legal professionals. Coordinating those discussions can reduce surprises and help ensure that business, personal, and retirement decisions are considered together.
Address Key-Person and Business Continuity Risks
A successful business may still be vulnerable if a founder, senior leader, or critical employee cannot continue in their role. Year-end is a practical time to identify the people whose responsibilities, relationships, technical knowledge, or decision-making authority would be difficult to replace.
Ask direct questions: Who can make key decisions if the owner is unavailable? Where are critical processes documented? Which client relationships depend on one person? Is there enough liquidity to manage a disruption? Are business continuity documents, ownership agreements, and insurance arrangements being reviewed by the appropriate professionals?
Key employee protection and continuity planning are not only operational concerns. They can affect business value, family security, retirement timing, and the ability to carry out a future transition. A coordinated review can help reveal whether personal and business plans rely too heavily on one individual.
Understand What Drives Business Value
For many owners, the company represents a substantial portion of net worth. Yet an assumed value is not the same as a defensible estimate of what a buyer, successor, or market participant may pay. A year-end review can identify the factors likely to influence value, including revenue consistency, profitability, customer concentration, leadership depth, documented systems, recurring income, debt, and the owner’s day-to-day role.
A formal valuation may not be necessary every year, but a business value assessment can provide a useful reference point for planning. It can also help you understand the gap between the value you may need to fund retirement and the value the business may reasonably support today.
For business owners in Schaumburg, Arlington Heights, Hoffman Estates, Barrington, Lake Zurich, Itasca, and nearby northwest suburbs, Purpose Financial Planning can help incorporate business value considerations into a broader financial plan. When appropriate, we can coordinate with valuation, tax, legal, and other professionals who address the technical aspects of a transaction or formal appraisal.
Define Succession and Transition Goals Early
Succession planning is not limited to choosing who will take over the business. It also involves deciding when you want to reduce responsibility, how much income you need after a transition, whether family or key employees may be involved, and what conditions would make a sale or transfer acceptable to you.
Start by writing down a preliminary transition timeline, even if it is several years away. Then consider the possible paths: a third-party sale, internal sale, family transfer, partial transition, or continued ownership with a professional management team. Each path can create different demands on cash flow, financing, estate planning coordination, and personal retirement resources.
The earlier these goals are clarified, the more time you have to strengthen the business, develop leadership, diversify personal assets, and prepare for decisions without urgency. Daniel Kaibel, CFP, and the team at Purpose Financial Planning use an education-first approach to help owners examine the financial implications of their choices in straightforward terms.
Connect Personal Retirement Plans to Business Value
A central question for many owners is: How do I plan for retirement if my business is my main asset? The answer begins with separating the value of the business from the income you expect it to provide after you step away. A business may have meaningful value, but that value can be affected by timing, market conditions, buyer financing, taxes, industry trends, and the degree to which the company depends on the owner.
Your personal retirement plan should test several scenarios. What happens if the business sells for less than expected? What if a transition takes longer than planned? How would retirement income be funded before, during, and after a sale? What assets outside the business are available to support spending, healthcare costs, and family goals?
Retirement income planning can help organize investment assets, future distributions, Social Security decisions, and business-sale proceeds into a coordinated retirement paycheck strategy. This approach can reduce the pressure to rely on one transaction or one valuation outcome. It can also help you make business decisions with a clearer understanding of how they affect personal financial independence.
Create a Practical Year-End Action List
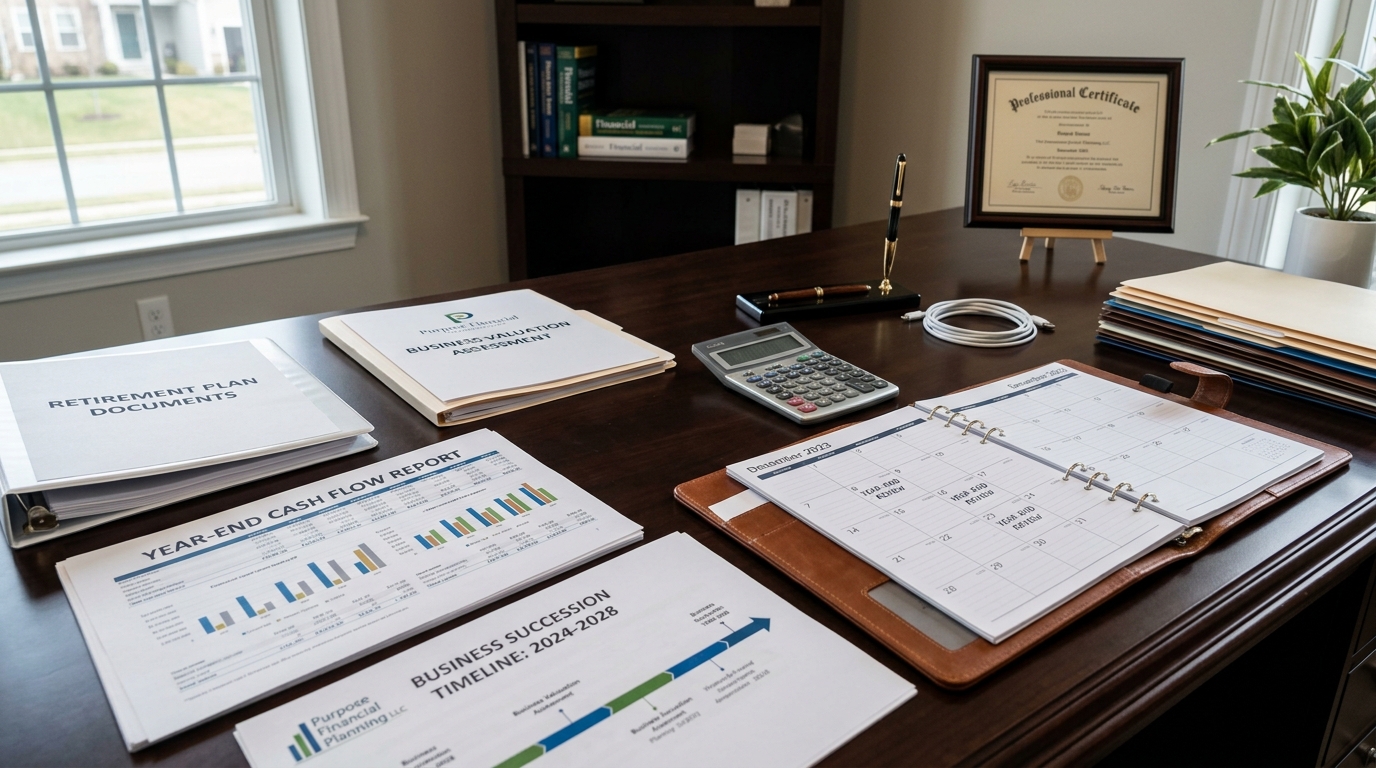
Before the year closes, gather current financial statements, debt information, retirement plan records, estimated tax payments, insurance summaries, ownership documents, and any prior valuation materials. Schedule conversations with your tax professional, attorney, insurance professional, and financial advisor as appropriate. Note the unanswered questions and the decisions that require action in the coming year.
A year-end review does not need to resolve every long-range issue at once. Its purpose is to establish a clear baseline, identify priorities, and create momentum toward a more resilient business and retirement plan.
FAQ
Why should business owners review cash flow at year-end?
A year-end cash flow review shows how the business supported operations, owner compensation, debt obligations, reinvestment, and savings during the year. It also helps owners identify whether their business and personal financial needs are being managed separately and sustainably.
When should I begin planning a business transition?
Planning is generally more effective when it begins well before a desired transition date. Starting early may provide more time to improve operations, develop leadership, document processes, diversify personal assets, and evaluate potential succession paths.
How does business value affect retirement planning?
Business value may be a major component of an owner’s net worth and a potential source of retirement funding. A personal retirement plan can test whether projected sale proceeds, investment assets, and other income sources are likely to support the lifestyle and goals you envision.
Do I need a formal business valuation every year?
Not necessarily. The appropriate frequency depends on your goals, ownership structure, industry, and transition timeline. Even when a formal valuation is not needed annually, reviewing the drivers of business value can be useful for long-term planning.
Can one advisor help coordinate retirement and business planning?
An independent financial planner can help connect business cash flow, retirement savings, investments, anticipated transition proceeds, and personal income needs within a comprehensive financial plan. Tax, legal, valuation, and insurance questions should be addressed with the qualified professionals in those areas.
If you are a Schaumburg-area business owner who wants to bring greater clarity to retirement planning, business value, and succession goals, contact Purpose Financial Planning LLC to schedule a consultation. We can help you organize the questions, evaluate the financial trade-offs, and build a personalized plan that supports both your business and your future.
Our Services
About the Author
Daniel Kaibel is the founder of Purpose Financial Planning, an independent financial planning firm serving Schaumburg, Illinois and the surrounding northwest suburbs. With more than 30 years of financial services experience, Dan has built the firm around straightforward advice, personalized guidance, and helping clients make informed decisions with greater confidence.
At Purpose Financial Planning, Dan works with retirees, business owners, families, and individuals to coordinate retirement planning, investment management, Social Security strategies, and long-term financial goals. His approach is simple: understand what matters most to the client, explain options in plain language, and create a clear path forward so financial decisions feel less overwhelming and more manageable.